Whether an Annual Limit Is Enough for a Bichon Frise
Navigating the world of pet insurance can feel like trying to untangle a ball of yarn after your mischievous Bichon Frise has had their way with it. Many of us sign up, thinking we're covered, only to later wonder if the "annual limit" on our policy will truly be enough when a health crisis hits. This guide is all about helping you understand those limits and whether they offer the protection your beloved Bichon genuinely needs, especially given their particular health predispositions.
Understanding Annual Limits in Pet Insurance
When you're looking at pet insurance, one of the first things you'll encounter is the concept of an "annual limit." It sounds straightforward, but its implications can be far-reaching, especially for a breed like the Bichon Frise, known for certain recurring health challenges. It's crucial to grasp exactly what this limit entails and how it might impact your ability to provide care.
What an Annual Limit Actually Means
An annual limit is quite simply the maximum amount of money your pet insurance company will reimburse you for eligible veterinary expenses within a single 12-month policy period. Think of it as a financial ceiling. Once your combined claims for the year reach that cap, the insurance company will no longer pay out for any further veterinary care until your policy renews for the next year. This means that if your Bichon incurs $10,000 in covered medical bills and your annual limit is $5,000, you will be responsible for the remaining $5,000, in addition to any deductibles or co-pays you already paid.
It’s important to remember that this limit resets with each new policy year. So, if you hit your limit in November, you'll be on the hook for any costs in December, but then in January, the slate is wiped clean, and your full annual limit is available again. However, this doesn't diminish the immediate financial strain if your pet needs extensive care late in a policy year. For a Bichon owner, where a single, complex issue or a series of smaller ones can quickly accumulate, understanding this ceiling is paramount.
Why Bichon Frises Need Special Consideration for Limits
Bichon Frises, as adorable and hardy as they appear, unfortunately, have a genetic predisposition to several health conditions that can be costly and, crucially, often recurring. This is where a standard annual limit can become a significant point of stress for pet parents. We're not talking about a one-off broken bone; we're talking about conditions that can require ongoing management or repeat interventions.
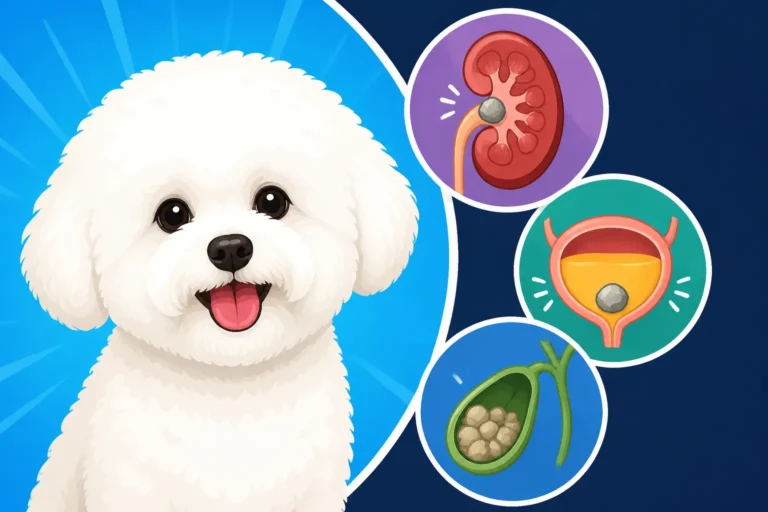
For example, urinary stones are notoriously common in Bichons, particularly calcium oxalate stones. These aren't usually a "dissolve with medication" kind of problem; they often require surgical removal. Why a Bichon Frise Forms Stones Twenty Times as Often and The Stone That Comes Back a Year After Bichon Frise Surgery are harsh realities for many. A single stone surgery can be a significant expense, but if your Bichon forms stones again within the same policy year, or even in consecutive years, those costs can rapidly exceed a modest annual limit. Similarly, allergies and atopic dermatitis are prevalent in the breed, often requiring lifelong medication, special shampoos, and frequent vet visits. While individual visits might seem small, they add up quickly. Consider What Treating a Bichon Frise's Skin Costs Every Year – these ongoing expenses can chip away at an annual limit, leaving little room for unexpected emergencies.
Calculating Potential Vet Costs for Your Bichon Frise
One of the biggest anxieties for any pet owner is the unknown cost of veterinary care, and for Bichon Frise parents, this concern is often amplified by the breed's specific health challenges. It’s not about if, but often when, certain issues might arise. Being prepared means having a realistic understanding of what those costs could entail and how quickly they can stack up against an annual insurance limit.
Common High-Cost Conditions in Bichons
Let's talk about the big-ticket items that can really put a dent in your wallet, or more ideally, your pet insurance. As we've mentioned, bladder stones are a prime offender for Bichons. The cost of diagnosis (X-rays, ultrasound like Whether an Ultrasound Finds a Bichon Frise's Stones, urine analysis), the surgery itself (cystotomy), and post-operative care can easily run into thousands of dollars. If your Bichon then requires a follow-up procedure or a different type of surgery, such as a urethrostomy for recurrent blockages, you're looking at another significant financial outlay. These aren't minor expenses; they're major surgical procedures requiring anesthesia, specialist care, and recovery monitoring.
Beyond stones, chronic conditions like atopic dermatitis or allergies are also common in Bichons. Managing these conditions often involves a multi-pronged approach: prescription medications (like Apoquel or Cytopoint injections, as discussed in Whether a Bichon Frise Can Take Apoquel Instead), specialized diets (which can be pricier than regular kibble), medicated baths, and regular dermatology consultations. While an individual dose of medication or a single bath might not seem like much, imagine these costs accumulating month after month, year after year. These treatments are essential for your Bichon's comfort and quality of life, but they steadily consume your annual limit. Companies like Healthy Paws are known for their comprehensive coverage, which can be invaluable for these types of ongoing conditions, potentially offering peace of mind where lower limits would quickly be exhausted. For prescription foods and specialty items, online retailers like Chewy often offer convenient delivery options for those necessary, recurring purchases.
The Impact of Recurring Issues
The real challenge with an annual limit for a Bichon Frise often comes down to the recurring nature of their common health problems. It's not just a one-and-done situation. Take those frustrating bladder stones. It's not uncommon for a Bichon to have one stone removed, only to develop another type of stone or a recurrence of the same type a year or two later. How Often a Bichon Frise's Stones Return highlights this unfortunate reality. Each new episode of stone formation means a fresh round of diagnostics, potential surgery, and post-operative care, all of which count towards your annual limit. If you have a $5,000 annual limit and one stone surgery costs $3,000, you only have $2,000 left for the rest of the year. If another stone develops that same year, you're largely out of pocket.
Similarly, conditions like luxating patellas (slipping kneecaps), while sometimes managed conservatively, often require surgical correction. If one knee is corrected, there's always the possibility that the other knee might develop issues later, leading to another expensive surgery. Or, if a Bichon develops a chronic illness like Cushing's disease, the monthly medication and regular monitoring tests can quickly add up, consuming a substantial portion of the annual limit each year. What Cushing's Medication Costs a Bichon Frise Owner Monthly gives a glimpse into this ongoing financial commitment. The cumulative financial stress of these recurring or chronic conditions is immense, and it’s a vital factor to consider when assessing if your chosen annual limit truly offers sufficient long-term protection.
How to Evaluate if an Annual Limit is Sufficient
Choosing the right pet insurance for your Bichon Frise isn't just about picking the lowest premium; it's about finding a policy that will genuinely support you through potential health challenges. Evaluating whether an annual limit is sufficient requires a careful look at your dog's unique circumstances, the types of policies available, and how various policy components interact.
Assessing Your Bichon's Individual Risk Factors
Every Bichon is an individual, but the breed as a whole carries certain genetic predispositions that should heavily influence your insurance choices. Before you even look at policy numbers, consider your Bichon's specific situation. How old are they? Younger Bichons might have fewer immediate health concerns, but a lifetime of potential issues lies ahead. An older Bichon, especially one past seven or eight, is more likely to start showing signs of conditions like Cushing's or dental disease. Caring for a Bichon Frise Past Eleven reminds us that senior care can be quite intensive.
Do you know your Bichon's genetic history? If their parents or grandparents had a history of bladder stones, luxating patellas, or severe allergies, your Bichon's risk might be higher. While no breeder can guarantee perfect health, a responsible breeder will often screen their dogs for common hereditary conditions and be transparent about any known issues in the lineage. Whether a Bichon Frise's Stone Risk Is Inherited touches on this crucial point. Also, think about their current health status. Have they had any minor issues already? Even small, seemingly insignificant issues can sometimes be early indicators of larger, more costly problems down the line. A healthy, active Bichon might initially seem low-risk, but factoring in breed-specific tendencies is paramount.
Comparing Different Policy Structures: Annual vs. Per-Condition vs. Lifetime
The type of annual limit you choose often dictates the overarching structure of your pet insurance policy. It's not a one-size-fits-all world, and understanding the nuances is vital for a Bichon owner.
-
Annual Limit Policies: As discussed, these policies have a maximum payout per 12-month period. Once you hit that ceiling, you're on your own for the rest of the year. For a Bichon that might face multiple surgeries for stones in quick succession, or ongoing, expensive allergy treatments, a lower annual limit can quickly be depleted. It provides coverage, but with a hard stop.
-
Per-Condition Limits: Some policies offer a maximum payout per condition over the lifetime of the pet, or per year. This means that your Bichon might have a $2,000 limit for bladder stones, a $1,500 limit for allergies, and so on. While this might seem appealing at first, consider that chronic conditions like allergies in a Bichon can easily exceed a per-condition limit over several years, forcing you to pay out of pocket for an ongoing issue. This structure can be particularly problematic for breeds prone to lifelong conditions.
-
Unlimited or Lifetime Policies: These are often considered the gold standard, especially for breeds with known health challenges like the Bichon Frise. An unlimited annual limit means there's no cap on how much the insurance company will reimburse you in a year, for eligible conditions. A lifetime policy often implies that once a condition is covered, it will continue to be covered for the duration of the pet's life, rather than being capped per condition or excluded after a certain number of claims. For a Bichon that might experience recurring bladder stones, or require lifelong management of Cushing's disease or severe allergies, an unlimited or high-limit lifetime policy offers the most comprehensive protection. This ensures that even if treatment for a condition extends over many years and costs thousands upon thousands, you're still supported. This kind of robust coverage, offered by providers like Healthy Paws, can be transformative for a Bichon Frise owner. Whether a Lifetime Policy Is Worth It for a Bichon Frise directly addresses this consideration.
The Role of Deductibles and Reimbursement Rates
Beyond the annual limit itself, the deductible and reimbursement rate are two other critical components that determine your out-of-pocket costs and how quickly you might approach your annual limit.
The deductible is the amount you pay out of pocket before your insurance coverage kicks in. This can be an annual deductible (you pay it once per policy year, regardless of how many different conditions are treated) or a per-incident deductible (you pay it for each new illness or injury). For a Bichon with multiple, distinct health issues in a year, an annual deductible is usually more favorable. A higher deductible means lower monthly premiums, but it also means you bear more of the initial cost each year before your insurance starts paying.
The reimbursement rate is the percentage of the covered vet bill that the insurance company will pay back to you after you've met your deductible. Common rates are 70%, 80%, or 90%. If you have an 80% reimbursement rate and a $1,000 vet bill after your deductible, the insurance will pay $800, and you'll pay $200. This $800 is then deducted from your annual limit. A lower reimbursement rate means you pay more of each bill, and consequently, your annual limit will be reached more slowly from the insurance company's perspective, but your personal out-of-pocket costs remain higher. Conversely, a higher reimbursement rate means the insurance company pays more, and your annual limit is consumed faster, but your financial burden is significantly less. When evaluating Whether an Annual Limit Is Enough for a Bichon Frise, you must consider how your chosen deductible and reimbursement rate will impact the real benefit you receive from that annual limit.
Strategies When Annual Limits Fall Short
It's a dreadful scenario no pet parent wants to face: your beloved Bichon Frise needs critical care, but you've already hit your pet insurance's annual limit. The emotional toll is immense, compounded by the sudden and unexpected financial burden. Understanding what happens in this situation and how to mitigate the risk is crucial for responsible pet ownership.
What Happens When You Hit Your Limit
When your Bichon's veterinary bills, even with your chosen reimbursement rate, accumulate to the point where they reach your policy's annual limit, the insurance company's obligation for that policy year ends. Any further covered medical expenses incurred for the remainder of that 12-month period become entirely your responsibility. Imagine your Bichon is recovering from a costly bladder stone surgery that consumed most of your $5,000 annual limit. Then, a few months later, they develop a severe, acute allergic reaction requiring emergency hospitalization and extensive treatment. If you've already exhausted your limit, those new, urgent bills—which could easily run into thousands—will fall squarely on your shoulders.
This can lead to heart-wrenching decisions, where the best medical care for your Bichon might be financially out of reach. It's a frustrating and terrifying position to be in, especially since many of the chronic and recurring conditions common in Bichons, like those stubborn stones or persistent allergies, don't conveniently wait for a new policy year to begin.
Exploring Higher Limits or Unlimited Plans
Given the potential for high and recurring vet costs with a Bichon Frise, many experienced owners and veterinarians will advocate for policies with higher annual limits or, ideally, unlimited coverage. While these plans typically come with higher monthly premiums, the peace of mind they offer is often invaluable. A plan with a $10,000 or $15,000 annual limit will provide a much larger buffer against multiple incidents or chronic conditions than a $5,000 limit. For a breed like the Bichon, prone to issues that can recur multiple times over their lifespan, a robust annual limit helps ensure that financial constraints don't dictate treatment choices.
Some top-tier providers, such as Healthy Paws, offer unlimited annual payouts, meaning there's no cap on eligible veterinary expenses. For a Bichon owner facing the prospect of multiple surgeries for Whether a Bichon Frise Can Have Repeat Surgeries or lifelong medication for What Pituitary Cushing's Does to a Bichon Frise, an unlimited plan removes a huge layer of financial worry. You know that as long as the condition is covered, you won't suddenly be cut off from support mid-year. This allows you to focus solely on your Bichon's recovery and well-being, rather than agonizing over mounting out-of-pocket costs.
Budgeting for the "What If" Scenarios
Even with the most comprehensive pet insurance, it’s always wise to budget for potential "what if" scenarios. No insurance covers everything, and there will always be deductibles and reimbursement percentages to consider. Creating a dedicated emergency fund for your Bichon is a fantastic complementary strategy. This fund can cover your deductible, the percentage not reimbursed by insurance, or any expenses that might fall outside your policy's coverage (e.g., pre-existing conditions not covered, or expenses incurred after hitting a lower annual limit).
Think of it as a safety net under your safety net. You could set aside a certain amount each month, perhaps into a high-yield savings account, specifically earmarked for your Bichon's health. This gives you greater flexibility and less stress if an unexpected vet bill arises, whether it's covered by insurance or not. Setting Money Aside for a Bichon Frise's Vet Bills is a practice that can alleviate a lot of the financial burden and ensure you can always provide the best care for your furry family member.
Here's a quick overview of how different policy features interact with your annual limit:
| Policy Feature | Description | Impact on Bichon Frise Owner (with recurring/costly issues) |
|---|---|---|
| Annual Limit | Max amount insurer pays in a 12-month period. | Lower limits (<$5-10k) can be quickly exhausted by single surgeries (stones, patellas) or chronic disease management (allergies, Cushing's), especially if recurring. |
| Per-Condition Limit | Max amount insurer pays per specific condition over pet's lifetime or annually. | Highly problematic for Bichons; chronic allergies or recurring stones can quickly hit these limits, leaving owners responsible for ongoing costs for the same issue. |
| Unlimited Annual Limit | No cap on total payouts within a policy year. | Ideal for Bichons. Provides comprehensive protection against high costs and recurring issues, minimizing out-of-pocket expenses beyond deductible/reimbursement. |
| Deductible | Amount owner pays before reimbursement begins. Can be annual or per-incident. | Annual deductible is generally better for Bichons with multiple issues in a year. Higher deductible = lower premium, but more upfront cost. |
| Reimbursement Rate | Percentage of covered costs insurer pays after deductible (e.g., 70%, 80%, 90%). | Higher rate (90%) significantly reduces out-of-pocket costs, but can make you hit a lower annual limit faster as the insurer pays more. |
| Lifetime Coverage | Policy covers conditions for the pet's entire life, often without per-condition caps. | Essential for Bichons prone to chronic or recurring conditions like stones, allergies, or diabetes. Ensures continuous coverage for long-term management. |
Ultimately, deciding whether an annual limit is enough for your Bichon Frise boils down to a realistic assessment of their breed-specific health risks and your personal financial comfort level. For a breed with known predispositions to expensive, chronic, and recurring conditions, opting for a higher annual limit or an unlimited plan often provides the most robust safety net. It’s an investment in your peace of mind and, more importantly, in your beloved Bichon's long-term health and happiness.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.